 The Market
By Chief Editor Clark for The Market MBA · Opinion / analysis
AI can still change the economy and be financed like a late-cycle bubble. The tell is in the debt, not the demos. Here’s what investors should watch next.
Two videos made the rounds on the same day, and they are more useful together than either is alone. On Mario Nawfal’s show, macro economist Henrik Zeberg tells interviewer Brandon Weichert that the AI-driven tech trade has “all the signs” of a bubble “and it’s going to burst.” In a separate breakdown, Thomas Kralow walks through the debt underneath that boom: cheaper AI, still-expensive chips and data centers, and a financing structure that is starting to show stress.
Our view is straightforward. The technology can be a genuine leap and the market can still be in a late-cycle credit bubble. The investment question is no longer “is AI real?” It is whether the cash this build-out is supposed to produce can service the debt already stacked underneath it — and whether that stress shows up in credit before it shows up in the index.
Zeberg is not arguing that AI is fake. He compares it to the steam engine and electrification, not to a new iPhone, and says people will overestimate what it does in one year and underestimate what it does in ten. He still calls the present setup a bubble: investors front-run a new technology, “wild projections” justify a capacity build, and demand arrives slower than the forecasts.
He also says the top is not in yet. Weichert cited a session in which Nvidia (NVDA) fell while the Nasdaq 100 rose; Zeberg read that as “late phase rotation” out of the leaders and into smaller stocks, not a broad crash. (Those session figures come from the interview, not from our own tape of the close.) He then argued that a 30% to 40% rally “could easily be ahead in a very short amount of time,” the way markets ran into the 2000 and 2007 peaks. A melt-up would not disprove the bubble. It would be the last chapter of one.
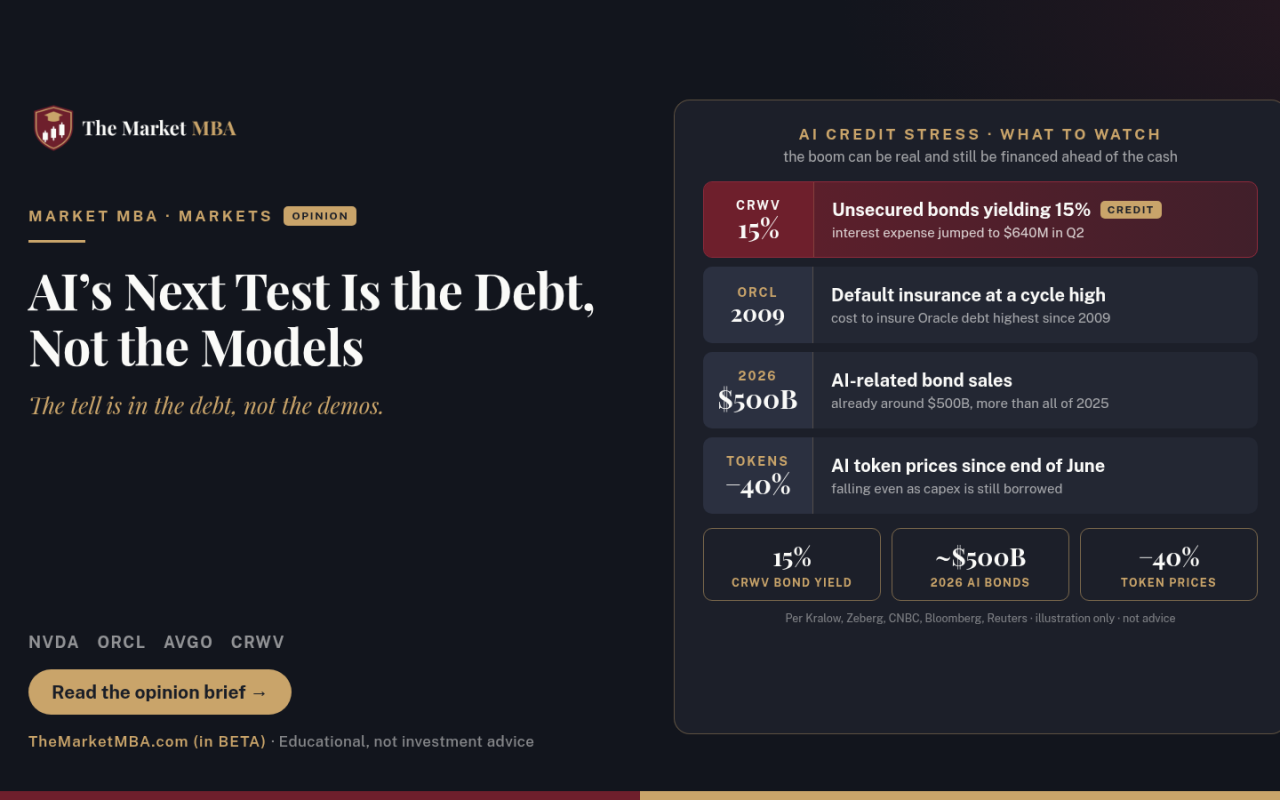
Kralow supplies the credit math. He says AI token prices are down about 40% since the end of June, while companies are still spending hundreds of billions on chips and data centers, “mostly with borrowed money.” He cites SpaceX, Broadcom (AVGO), and Oracle (ORCL) trying to borrow tens of billions at once for AI chips, including a reported SpaceX package of about $40 billion for Nvidia chips that matches contemporary reporting on the talks. Reuters, via Investing.com He also says 2026 AI-related bond sales were already around $500 billion, more than all of 2025, in line with Goldman Sachs estimates cited in the press. Reuters Breakingviews
The more important point is the mismatch. Kralow argues that chips “lose real value within a few years,” while a lot of the debt is locked in for a decade or more. He describes “circular financing,” in which Nvidia invests in or lends to the same companies that then buy Nvidia chips, so some of the revenue everyone is cheering is “just money moving in a circle.” He says this is not a Ponzi scheme. It does not have to be. Vendor financing was enough to wreck Lucent and Nortel in the late 1990s, and he draws that parallel on purpose.
Some of the stress is already visible. He pointed to CoreWeave (CRWV) unsecured bonds yielding 15%, and to interest expense jumping from $267 million to $640 million year over year. That $640 million figure matches CoreWeave’s reported net interest for the second quarter of 2026 — a quarterly number, not a full-year total. CNBC, Oct. 14 He also said the cost to insure Oracle’s debt against default had reached its highest level since 2009, a claim Bloomberg has reported in this cycle. Bloomberg
Zeberg’s crash sequence is the macro version of the same map. AI debt is “the fuse.” From there, stress moves into private credit — “debt out there that is not on the balance books” — and then into the consumer. Off-balance-sheet structures, including the vehicle Kralow says Oracle is using so chip debt “never touches Oracle’s own books,” make that fuse harder to see in the headline numbers.
The strongest counterargument is not that the bears have the facts wrong. It is that cheaper AI can create its own demand. Kralow states the bull case fairly: Jevons paradox, and a Citadel August note that, in his telling, found AI spending per employee at the top 1% of firms up 49% month over month in July. If usage grows faster than prices fall, the debt can still work. Zeberg leaves room for that future: he calls AI one of the great productivity leaps and says a late melt-up can still arrive first. Even Kralow’s tape cuts the other way. He says the share of usage going to the most expensive frontier models slipped from about 53% to 45%, and that the top 1% of spenders cut per-employee spending by nearly 10% in August — a “crack in the AI thesis,” in a line he attributes to Ramp’s chief economist. That is not proof the boom is over. It is proof the race between usage and price is the whole bet.
What should investors watch from here? First, credit, not just the Nasdaq print: neocloud yields, Oracle default-insurance costs, and any further push of AI capex into private credit or off-balance-sheet vehicles. Second, token prices and utilization versus the cost of the build-out. Third, the consumer and the jobs data underneath Zeberg’s “rolling over” claim. He cited a 2025 payroll revision of about 1 million jobs; the Bureau of Labor Statistics’ final March 2025 benchmark was a downward revision of 898,000, close to that rounding but not identical. BLS His figure of about 16,000 fully revised jobs a month was not independently confirmed here and should be treated as his estimate. Fourth, breadth: if Nvidia keeps leaking while smaller stocks catch a bid, treat it as late-cycle rotation until the credit market says otherwise.
AI is going to change how the economy produces and works. That can be true, and it can still be true that this cycle is being financed ahead of the cash flow. The last people who needed that distinction were the investors who owned real internet technology in 2000 and still lost a fortune on the debt and the multiples around it.
This is opinion and analysis, not financial advice, and not a recommendation to buy or sell any security.
Chief Editor Clark
The Market MBA
NFA. This article is for educational purposes only and is not financial advice.
For education and entertainment only. Not financial advice.