 The Market
By Chief Editor Clark for The Market MBA
Most AI headlines are about chips and the companies that design them. Thursday night, two companies further down the supply chain reported: Cisco (CSCO), which sells the switches, routers and optics that link AI servers together, and Applied Materials (AMAT), which sells the machines that make chips. Both posted records. Here is how to read them, and what they say about where AI money is going.
The AI spending chain, in one paragraph
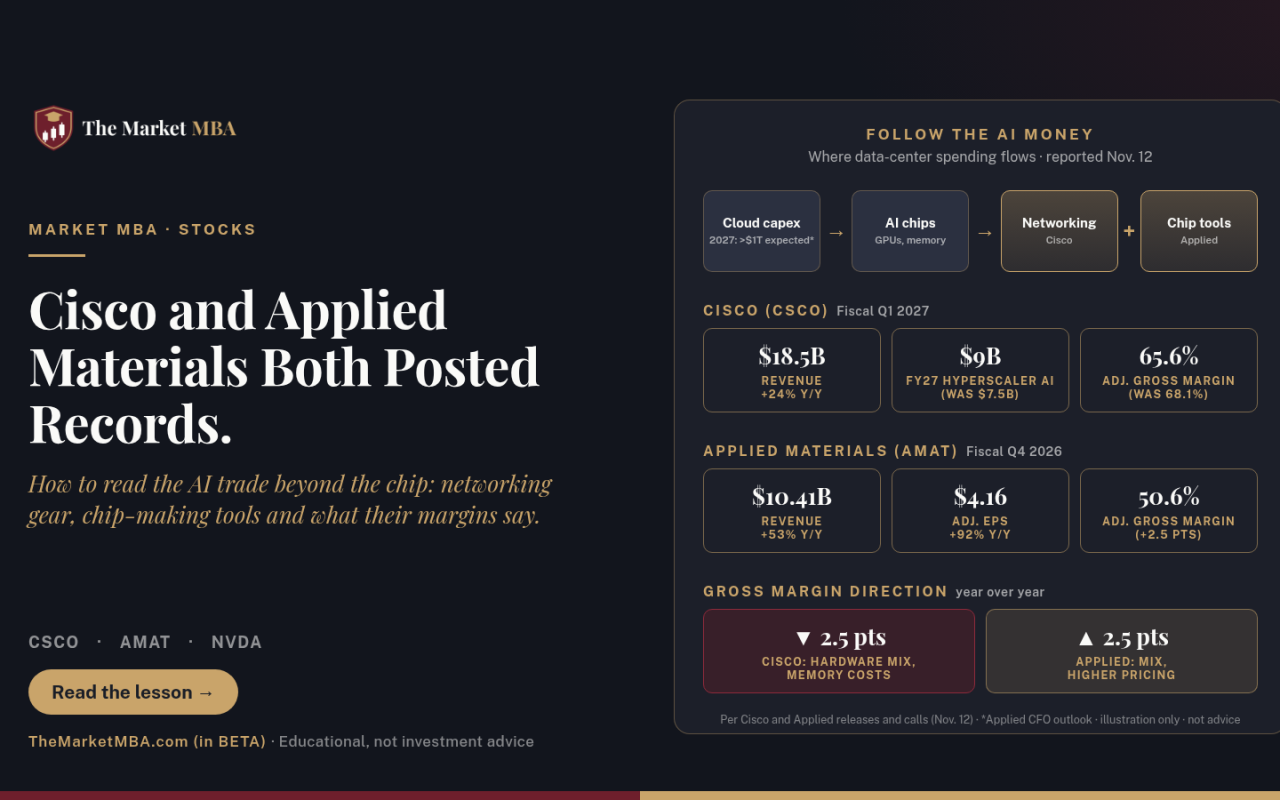
Think of AI spending as money flowing down a pipe. Cloud giants (the “hyperscalers”) spend on data centers. That money buys chips, but also the network that connects thousands of chips, and every chip has to be manufactured on tools made by companies like Applied. Applied’s CFO said on the call that cloud capital spending is expected to rise more than 50% in 2027 to “well over $1 trillion,” and its CEO said about 60% of the capital cost of an AI data center is silicon (Applied Q4 call). Cisco and Applied sit on two different branches of that pipe, so their reports are a check on whether the money is still flowing.
Cisco: AI networking is now a real business
Cisco reported fiscal first-quarter revenue of $18.5 billion, up 24% from a year earlier, and adjusted earnings of $1.40 a share, up 40% (Cisco release). Analysts polled by LSEG expected $18.1 billion and $1.33 (CNBC). Cisco called it its fastest revenue and adjusted EPS growth in more than 15 years. Product revenue jumped 32%, led by networking, up 43% (Cisco).
The headline number for AI watchers: Cisco now expects $9 billion of AI infrastructure revenue from hyperscalers this fiscal year, up from $7.5 billion it forecast 90 days ago and more than double fiscal 2026 (Reuters via CNA; Cisco Q1 call). It raised its full-year revenue forecast to $74.8 billion to $75.8 billion, from $72.2 billion to $73.4 billion (Reuters via CNA). CEO Chuck Robbins called it “the very early stages of a multi-year networking supercycle.”
One detail ties to our recent neocloud coverage. Asked about exposure to neoclouds such as Nebius and CoreWeave, Robbins called it “relatively immaterial” and said Cisco has been “very conservative relative to credit situations”; the $9 billion target counts only hyperscalers (Cisco Q1 call). In other words, Cisco’s AI growth is tied to the biggest, best-funded buyers.
Lesson 1: Revenue mix changes margins
Here is the part a quick headline skim misses. Cisco’s adjusted gross margin fell to 65.6% from 68.1% a year earlier (Cisco). The CFO said adjusted product gross margin fell 3.5 points, “primarily driven by higher hardware mix and elevated memory costs” (Cisco Q1 call). Hardware sold to hyperscalers earns less per dollar than software and services, and services grew just 1% (Cisco).
So why did profit grow faster than sales? Operating leverage. Adjusted operating expenses rose only 2% while revenue rose 24%, pushing adjusted operating margin to a record 37.8% (Cisco). A lower gross margin on much more revenue, with costs held flat, can still mean far more profit. When a company’s mix shifts, check both margins, not just one.
Applied Materials: the bottleneck is factory space, not demand
Applied reported fiscal fourth-quarter revenue of $10.41 billion, up 53% from a year earlier, and record adjusted EPS of $4.16, up 92% (Applied release). Analysts polled by FactSet expected $4.06 (Investor’s Business Daily). For fiscal 2026, revenue rose 21% to $34.45 billion (Applied). It guided the current quarter to $11.1 billion of revenue, plus or minus $500 million, and adjusted EPS of $4.35, plus or minus 20 cents (Applied).
Management expects wafer fab equipment spending, the industry’s total budget for chipmaking tools, to grow more than 30% in 2027. The CFO said the limit on growth is how fast chipmakers can build clean rooms, the dust-free factory floors where tools are installed. CEO Gary Dickerson said no customer is asking to delay deliveries: “Nobody is saying that they’re not wanting the tools as fast as we can get them” (Applied Q4 call).
Lesson 2: Pricing power shows up in gross margin
Applied’s story is the mirror image of Cisco’s. Its adjusted gross margin rose 2.5 points from a year earlier to 50.6%, which the CFO credited to “favorable mix effects and higher pricing,” and called the company’s 14th straight quarter of year-over-year gross margin expansion (Applied Q4 call; Applied). When demand outruns supply, sellers of hard-to-replace equipment can raise prices. A rising gross margin during a boom is one of the clearest signs of pricing power.
Lesson 3: A record quarter does not guarantee a pop
Neither stock exploded. Cisco closed the regular session at $102.01, up 1.24%, and traded about 1.4% lower after hours in one Investing.com snapshot after earlier gains reported by CNBC; it is up about 35% this year (Investing.com; CNBC). Applied fell 3.58% during the day to $380.95, before its report, and edged up about 0.5% after hours (Investing.com).
The reason is expectations. When a stock has already run up on an AI story, a beat is partly “priced in,” and investors start asking about the next year. Applied’s beat was about 2.5% on EPS and about 1% on revenue; Cisco’s was about 6% on EPS (Investing.com; Investing.com). Solid, not shocking. Thursday’s backdrop mattered too: chip stocks were already shaky after Nvidia (NVDA) said CEO Jensen Huang had resigned, with CFO Colette Kress named interim CEO (Nvidia).
What to watch
- Nov. 17: Nvidia’s quarterly report, its first under an interim CEO. If its outlook holds up, it supports the spending these two companies are seeing.
- Cisco’s gross margin: management guided this quarter to 65% to 66% and said the full year should be “just shy of 65%” (Cisco Q1 call). A bigger drop would mean hardware mix and memory costs are biting harder.
- Applied’s output: it plans to double systems output from fourth-quarter 2026 levels by 2028, and said China should be under 25% of business in 2027 (Applied Q4 call).
- Friday: producer price inflation, which feeds into interest-rate expectations and how much investors will pay for growth stocks.
The bottom line
Cisco and Applied are a read on the AI build-out from the plumbing up, and both say demand is still rising. The lesson for investors is in the margins: Cisco is growing faster by selling more lower-margin hardware, while Applied is growing and raising prices at the same time. Same boom, two very different ways of getting paid.
Sources
- Cisco: Cisco Reports First Quarter Earnings (Nov. 12)
- CNBC: Cisco beats on earnings, says AI infrastructure revenue will double (Nov. 12)
- Reuters via CNA: Cisco lifts annual revenue forecast on strong AI networking demand (Nov. 12)
- Investing.com: Cisco Q1 FY2027 earnings call transcript (Nov. 12)
- Applied Materials: Fourth Quarter and Fiscal Year 2026 Results (Nov. 12)
- Investing.com: Applied Materials Q4 2026 earnings call transcript (Nov. 12)
- Investor’s Business Daily: Applied Materials beats fiscal Q4 targets (Nov. 12)
- Nvidia: NVIDIA Announces CEO Transition (Nov. 12)
- The Market MBA: Nebius Q3 quality-of-beat lesson (Nov. 12)
- The Market MBA: CoreWeave Q3 earnings breakdown (Nov. 10)
Not financial advice. This article is for educational purposes only. Nothing here is a recommendation to buy or sell any security.
For education and entertainment only. Not financial advice.